Published October 21, 2026
Halal Mortgage Utah: How to Buy a Home With Islamic Financing in 2026
Yes, you can get a halal mortgage in Utah in 2026 if you want to buy a home without paying interest (riba). Devon Bank offers Murabaha financing in Utah, and IjaraCDC offers lease-to-own Ijara programs through licensed investors in all 50 states, with paths starting at 0% to 3.5% down depending on the program. Each is structured to comply with Islamic finance principles; consult a scholar about which fits your convictions. Here's how each works, what you'll need to qualify, and how to plan your purchase from Logan to Orem.
WHAT BUYING A HOME ISLAMICALLY MEANS
For many Muslim families, the main concern with a standard mortgage is riba, the interest charged on borrowed money. Islamic home financing replaces the loan with a different kind of transaction: a sale at an agreed markup, a lease that leads to ownership, or a shared ownership partnership.
This guide is informational, not a religious ruling. Scholars differ on which structures are acceptable, so please review any product with your own imam or scholar and ask about the provider's Shariah board before you sign.
ISLAMIC HOME FINANCING PROVIDERS THAT SERVE UTAH IN 2026
We checked provider licensing pages in October 2026. State lists change, so confirm directly before you apply.
Devon Bank (Murabaha)
Devon Bank lists Utah among the states where it offers Murabaha, which it has provided since 2003 for both purchases and refinances. The bank (NMLS #412368) describes its financing as "not a loan" but an installment sale (or a lease, depending on the structure). It says its profit rate is the same as an equivalent traditional mortgage, that some closing costs run higher (for example, recording two deeds), and that late fees beyond its actual costs go to charity.
IjaraCDC (Ijara, lease-to-own)
IjaraCDC is a Michigan nonprofit that says it is not a lender or broker. It works through licensed lenders and investors it says cover all 50 states, using a lease-to-own model in which the home is held in a trust while you make payments. Ask which licensed partner would fund a Utah purchase.
Not currently available in Utah
Guidance Residential is one of the best-known names in the space, but Utah is not on Guidance Residential's published list of licensed states. UIF Corporation (NMLS #93460), which absorbed LARIBA on April 1, 2026, does not list Utah among its states.
MURABAHA, IJARA AND MUSHARAKA IN PLAIN ENGLISH
Murabaha: a sale at a fixed markup
The provider buys the home and immediately sells it to you at a higher, agreed price that you pay in installments. With Devon Bank, you hold title at closing and the price is fixed, so it can't rise later.
Ijara: lease now, own later
The home is held (with IjaraCDC, in a trust), and you pay monthly amounts that combine rent with payments toward ownership. When the term is complete, the home is yours.
Diminishing musharaka: shared ownership
You and the provider co-own the home. Each month you pay rent on the provider's share and buy a little more of it, until you own it all. Guidance Residential and UIF use this model, but neither currently serves Utah.
DOWN PAYMENT AND CREDIT REQUIREMENTS
IjaraCDC publishes program minimums that mirror familiar loan types:
- Conventional: 620 credit score, 3% down
- FHA: 520 credit score, 3.5% down
- VA: 620 credit score, 0% down
- USDA: 600 credit score, 0% down
- Jumbo: 680 credit score, 10% down
- Investment property: 620 credit score, 15% to 25% down
Devon Bank advertises a "low down payment" but doesn't publish a minimum, so ask for a written quote. IjaraCDC's main programs also ask for at least two years of employment or self-employment history. See our Utah financing guide for more on preparing to buy.
OTHER OPTIONS WITHOUT FINANCING: CASH AND FAMILY POOLING
Some families skip financing altogether. Paying cash makes your offer strong in competitive Wasatch Front neighborhoods and avoids financing questions entirely. Others pool savings among relatives and co-own the home. If you go this route, put the arrangement in writing, decide how title will be held, and talk with a Utah real estate attorney so everyone's share is protected.
UTAH HOUSING DOWN PAYMENT ASSISTANCE: WHY IT DOESN'T FIT
Utah Housing Corporation's down payment assistance is a second mortgage: a Traditional DPA of up to 6% of the first loan (capped at $27,500, 30-year fixed at 1% above the first-mortgage rate, not to exceed 8%) or a Deferred DPA of up to 3.5% (3.5% deferred interest, no monthly payment). It is available only with a Utah Housing first mortgage (FirstHome, FHA/VA or HFA Advantage), which have credit minimums of 620 to 680 and income limits. Because it is interest-bearing and must be closed with a UHC first loan, it can't be combined with the Islamic financing providers above. Confirm current rules with UHC.
TITLE AND CLOSING NOTES
Islamic financing closes a little differently. With Murabaha, two deeds may be recorded, which adds a modest cost. With Ijara, a trust may hold title until you finish paying. Let your title company know early which structure you're using, budget extra time for document review, and read every page before signing. Our home buying guide walks through each step of a Utah closing.
WHERE TO BUY NEAR UTAH'S MOSQUES
Being close to your masjid matters for Jumu'ah, Ramadan nights and weekend school. A few community anchors to start your search:
- Logan Islamic Center, 748 N 600 E, Logan
- Masjid Al Noor, 740 S 700 E, Salt Lake City
- Khadeeja Islamic Center, 1019 W Parkway Ave, West Valley City
- Utah Islamic Center, 984 W 9000 S, West Jordan, which describes itself as Utah's largest mosque
- Utah Valley Islamic Center (Al Sahaba Mosque), 352 E 900 S, Orem, a short drive for Provo and BYU or UVU families
West Jordan, West Valley City and Sugar House each offer a mix of townhomes and single-family homes, while Orem and Provo give Utah County buyers more space for the money.
NEXT STEPS
- Talk to your scholar about which structure fits your convictions.
- Contact a provider for a pre-qualification and a written cost estimate.
- Talk to a Red Sign agent. Founded in 2008, Red Sign has helped with about 3,500 transactions and earned 1,950+ five-star reviews. We serve buyers across Utah from our office at KW Westfield in Orem and are glad to help you find a home near your community and schedule around the steps of Islamic financing.
FREQUENTLY ASKED QUESTIONS
Can I get a halal mortgage in Utah?
Yes, Utah buyers have options structured to comply with Islamic finance principles. Devon Bank offers Murabaha in Utah, and IjaraCDC offers Ijara programs through licensed investors in all 50 states. Consult a scholar, and confirm availability with each provider before applying.
Is Islamic home financing more expensive than a regular mortgage?
Not always. Devon Bank says its profit rate matches an equivalent traditional mortgage, though some closing costs, such as recording a second deed, can be higher. Compare full written quotes.
How much do I need to put down?
It depends on the program. IjaraCDC lists 0% for VA and USDA, 3% for conventional and 3.5% for FHA. Devon Bank doesn't publish a minimum.
Is Guidance Residential available in Utah?
Not currently. Utah is not on Guidance Residential's published list of licensed states.
Is Murabaha or Ijara halal?
Many scholars accept these structures, but opinions differ. Ask your scholar and review the provider's Shariah board before deciding.
Ready to start? Connect with a Red Sign agent today, or if you already own a home, ask us for a free home value report.
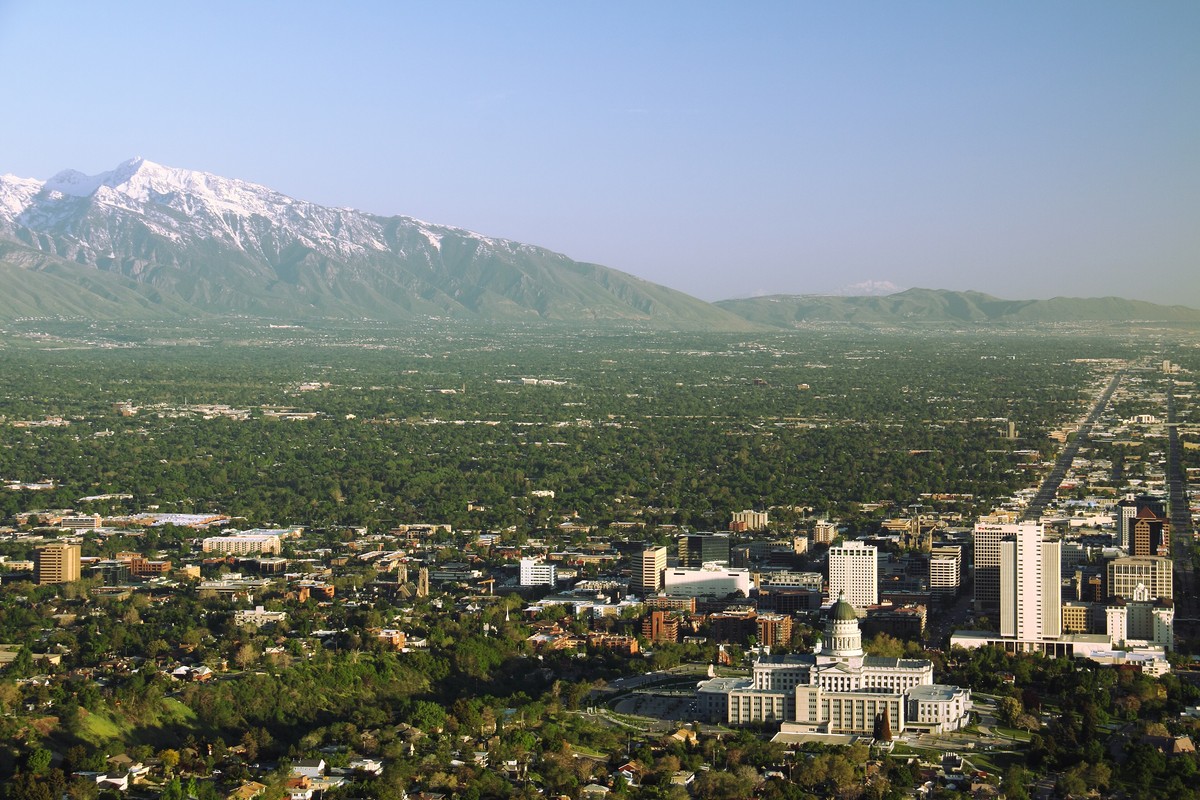
Featured image: Photo: Andrew Smith / Wikimedia Commons, CC BY-SA 2.0; cropped.
In This Article
Buying Islamically Utah Providers Financing Types Explained Down Payment and Credit Cash and Family Pooling Why DPA Doesn't Fit Title and Closing Utah Mosques Next Steps FAQHalal Financing Questions?
Talk to a Red Sign agent
We'll help you plan your search and time every step of your Murabaha or Ijara closing.
Let's Talk (801) 733 7446 What's my home worth? →